Fossil Group’s Turnaround, Measured Against the 2023 Letters to Its Board
- Published
- November 16, 2026
- Reading time
- 14 min
On November 10, 2026, Fossil Group, Inc. (NASDAQ: FOSL) reported net income of $11.7 million for the quarter ended October 3, 2026, against a net loss of $39.9 million in the same quarter a year earlier.¹ Gross margin was 59.8%, up from 49.0%. Operating income was $25.3 million, against an operating loss of $21.7 million. Net sales rose 0.4%, to $271.2 million, and the company raised its outlook for the year to net sales of $980 million to $990 million and an adjusted operating margin of 5.5% to 6.5%.¹ The next day the shares closed at $9.97, up 26.68%.²
Between March 22, 2024, the last trading day before Fossil agreed to put a shareholder’s nominee on its board, and the close on November 13, 2026, the price of Fossil common stock rose 858.0%.³
The engagement that produced that board seat was conducted by The Buxton Helmsley Group, Inc. (“BHG”), a company separate from Buxton Helmsley, Inc., and was led by Alexander Parker, who now leads Buxton Helmsley. BHG’s correspondence with Fossil’s board, and Fossil’s replies, are published in full on the campaign page.⁴ Below, each request in that correspondence is set beside what Fossil has since filed.
Where Fossil stood in September 2023
When BHG first wrote to the board on September 15, 2023, Fossil’s stock had lost, by BHG’s count, about 97% of its value since its Chief Executive Officer, Kosta Kartsotis, was named Chairman in May 2010.⁵ No director or executive officer had bought a share in the open market in the three years before that letter.⁴ ⁵ By November, according to BHG’s letter of November 28, 2023, the stock had no sell-side analyst actively covering it.⁴
The company had a cost program underway, which it called “Transform and Grow.” BHG pointed out in its first letter that Fossil’s market value was then “just over” the roughly $100 million of operating improvement the company had forecast for that program on August 9, 2023, so that the price gave almost no value to anything beyond that program.⁴ In its letter of October 10, 2023, BHG put the stock at about 30% of the company’s certified net asset value.⁴
For fiscal 2023, Fossil reported net sales of $1.41 billion, down 16%, an operating loss of $143 million, and a net loss of $157 million.⁶ It also had $150 million of 7.00% senior notes due on November 30, 2026.¹⁹ BHG’s first letter quoted the company’s own statement that its cash and credit lines would cover its needs “for the foreseeable future, not including the maturities of long-term debt,” and asked what the company was doing about those maturities.⁴
The first letter and the company’s answers
The September 15 letter put fourteen numbered questions to the board. The first group asked whether the company was following the accounting policies it had stated in its own annual report: whether impairment had been recognized wherever its policy said it would be, whether accumulated depreciation was fully reflected, and whether the company carried any material contingent liability.⁴ The second group was about the balance sheet and capital allocation. Why had no shares been bought back in twelve months under a program the board had already approved, when the stock traded at a deep discount to book value? Why had no insider bought stock? Would the company add or substitute a credit facility tied to its overall debt-to-capitalization ratio, use it to buy back its 7.00% notes due November 30, 2026, which traded below face value, and say publicly that it would consider offers for the company? How many of its stores had made money over the past year, and would the ones that had not be closed?⁴
Fossil’s Chief Financial Officer, Sunil Doshi, answered for the company. Its first reply, dated September 28, pointed BHG back to the filings that had prompted the questions, and BHG wrote the next day that the company had “failed to answer every single one of them.”⁴ A second reply on October 6 answered more of them, and a third on October 16 affirmed that “the Company and its policies comply with U.S. GAAP, including ASC 350 and ASC 360.”⁴
This piece does not suggest Fossil’s financial statements were wrong, and nothing the company has reported since suggests they were. The questions about accounting were there to establish whether the numbers could be relied on before more capital went into the stock. The company answered the accounting questions; it declined the ones about value. Asked on October 10 to affirm that its filed financial statements represented management’s best estimate of the company’s value, and that it would not later treat the stock market’s lower valuation as the truer one, the company replied on October 16 that it “is not required under U.S. GAAP, U.S. securities laws or other applicable law to provide its view on market valuation.”⁴ Asked why it would not appraise and disclose any real estate worth more than its carrying value, so that the extra value could support more borrowing, it referred BHG to the list of properties in its annual report.⁴
In its letter of September 27, 2023, BHG told the board that it remained confident the shares had “an intrinsic value of at least $7/share.”⁴ They closed at $9.97 on November 11, 2026.²
The nomination and the cooperation agreement
Five months of letters did not change the company’s course. On October 10, 2023, BHG wrote that if directors would not buy the company’s stock with their own money, the board “needs to be sizably replaced by shareholders,” and on November 28, it told the board that Mr. Doshi “would be wise to resign.”⁴
On February 16, 2024, BHG delivered notice that it would nominate four candidates for election at the 2024 annual meeting, and on February 20 it announced them: Pamela B. Corrie, a former Weil, Gotshal & Manges lawyer who had spent twenty-five years in corporate turnarounds and restructurings; Charles Garcia, formerly a managing director at Citadel; Deirdre A. O’Connor, who had spent more than ten years at the U.S. Department of Justice; and Rumbi B. Petrozzello, a forensic accountant and former president of the New York State Society of CPAs.⁵ BHG then held about 1.4% of the stock.⁵ ⁷ On February 26, it served a demand to inspect the company’s books and records under Section 220 of the Delaware General Corporation Law.⁸
On March 13, 2024, Fossil reported its fiscal 2023 results, announced that Mr. Kartsotis had stepped down as Chief Executive Officer and as a director, and announced a strategic review of its business and capital structure.⁶ ⁹ On March 24, thirty-seven days after the nomination notice and twenty-seven days after the books-and-records demand, the company entered into a cooperation agreement with BHG and appointed Ms. Corrie to the board and to its Nominating and Corporate Governance Committee.¹⁰ ¹¹ BHG withdrew its nominations and its demand, and accepted a standstill and voting commitments.¹⁰ The company appointed a second turnaround specialist, Eugene I. Davis, to the board the same day.¹¹
BHG took no fee and no premium under the agreement, and its holding was not bought back. The one payment the agreement provided was reimbursement of documented expenses, capped at $250,000, which fell about $100,000 short of what the engagement had cost.¹⁰
Ms. Corrie’s seat
Ms. Corrie was one of nine directors the board nominated for election at the 2024 annual meeting.¹¹ She owed her duties to the company and all of its stockholders, and she exercised her own judgment in the boardroom, as the law requires. Nothing in this piece comes from inside that boardroom, nor could it; it comes from what BHG wrote before she joined and what Fossil has filed since.
The seat was on the Nominating and Corporate Governance Committee, which decides how a board is composed and refreshed. The problem BHG described was not one accounting treatment that a single filing could correct. In BHG’s view, the problem was who was accountable for the company’s direction. BHG nominated Ms. Corrie because the situation needed a turnaround director, and her prior board seats (among them Pier 1 Imports, Lord & Taylor, and Bed Bath & Beyond, several in her capacity as a restructuring professional) reflected that work.⁵
She served on Fossil’s board until the company’s 2026 annual meeting on October 2, 2026, at which she was not among the seven directors elected.¹² Ms. Corrie now serves on Buxton Helmsley’s Expert Advisory Board.
What BHG asked for and what Fossil did
Exhibit 1 sets each measure BHG asked for in its published correspondence beside what Fossil did, with the date of the company’s own announcement.
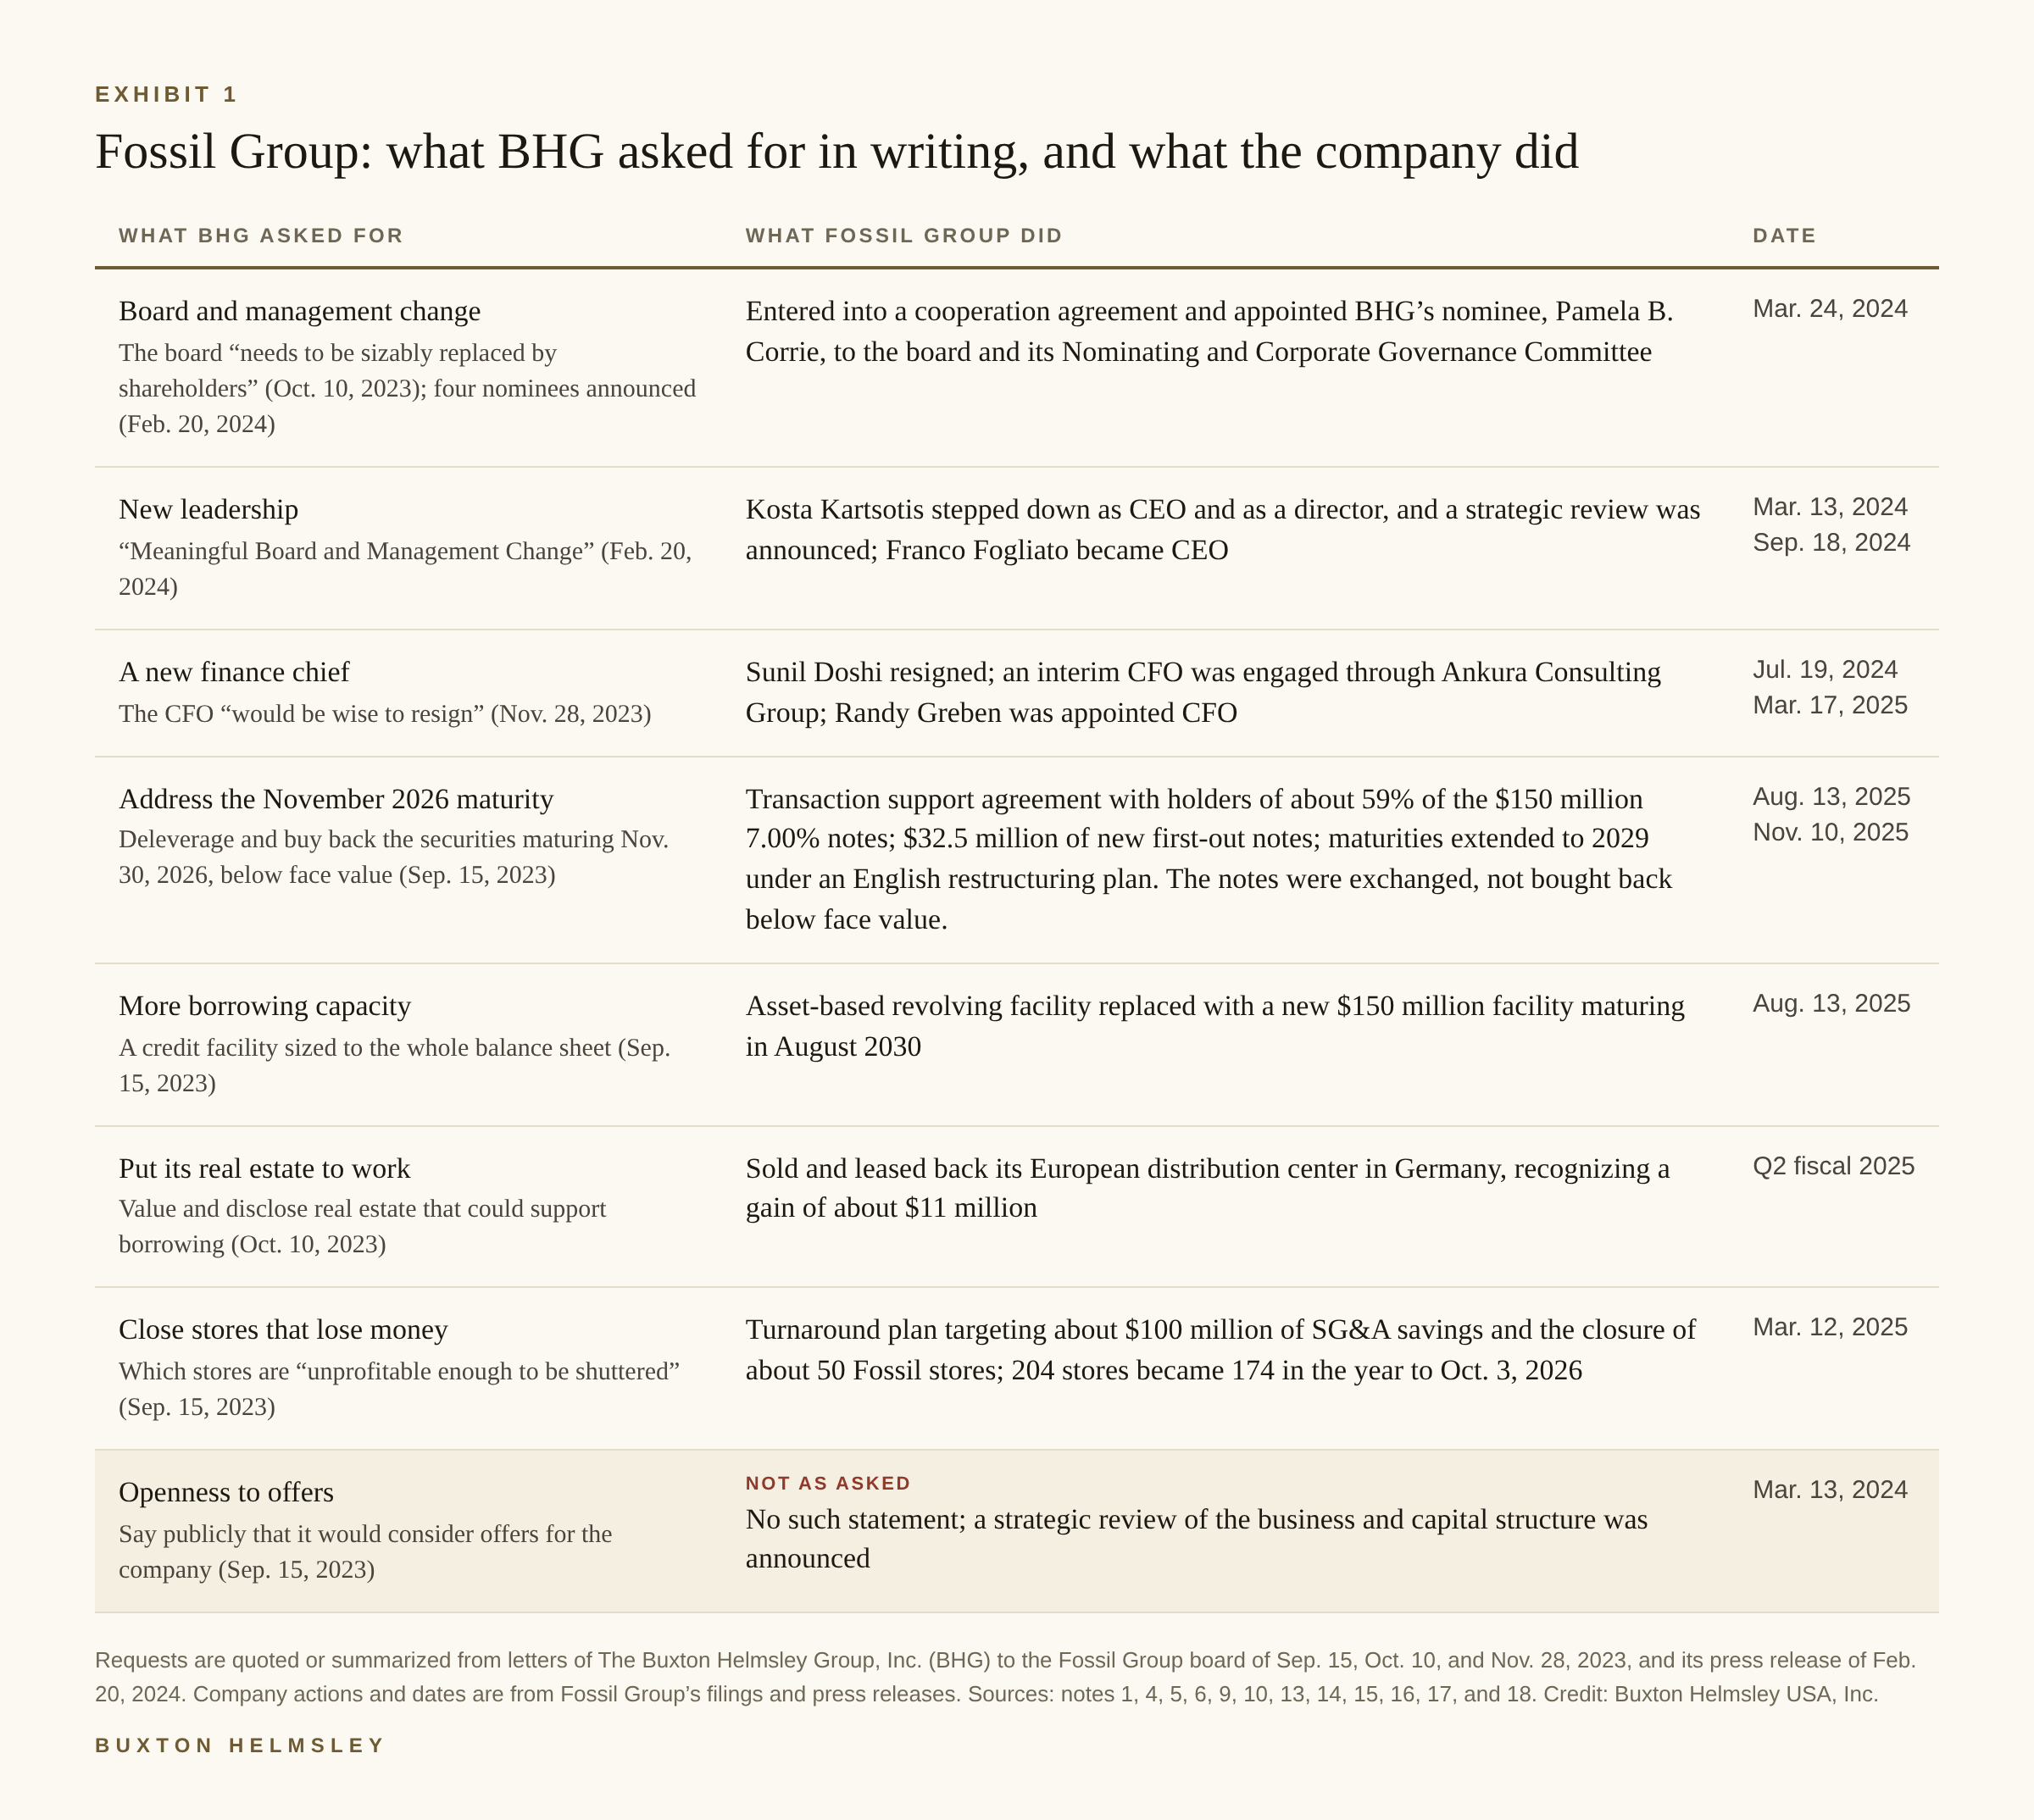
On June 25, 2024, Mr. Doshi notified the company that he would resign effective July 19, and Fossil engaged Ankura Consulting Group to provide an interim Chief Financial Officer.¹³ Randy Greben became Chief Financial Officer on March 17, 2025.¹⁵
Fossil named Franco Fogliato, formerly chief executive of Salomon, as Chief Executive Officer effective September 18, 2024.¹⁴ In March 2025, the company announced a turnaround plan built on three pillars: refocusing on its core business, rightsizing its cost structure, and strengthening its balance sheet.¹⁵ It set out to cut selling, general, and administrative expense by about $100 million in 2025 against 2024, through a corporate workforce reduction, a move to distributors in smaller international markets, and the closure of about 50 Fossil stores.¹⁵ Its store count went from 204 to 174 over the twelve months to October 3, 2026.¹
BHG had asked the company to value its real estate and borrow against it. In the second quarter of fiscal 2025, Fossil sold its European distribution center in Germany and leased it back, recognizing a gain of about $11 million, and divested equipment from a Swiss manufacturing facility.¹⁶ ¹
The largest step concerned the notes. On August 13, 2025, Fossil entered into a transaction support agreement with holders of about 59% of its 7.00% notes due 2026, under which the notes would be exchanged for new notes maturing in 2029, supported by $32.5 million of new first-out secured notes.¹⁷ At the same time, it replaced its asset-based revolving credit facility with a new $150 million facility maturing in August 2030.¹⁷ When the exchange offer fell short of its 90% participation threshold, the company completed the restructuring through a plan sanctioned by the High Court of England and Wales on November 10, 2025, recognized two days later by a U.S. bankruptcy court under Chapter 15.¹⁸ ¹⁹ Counsel on the transaction described it as the first known instance of a U.S.-listed company restructuring U.S.-law debt through an English plan.¹⁸
Not everything happened in the form BHG proposed. The 2026 notes were exchanged and extended, not bought back below face value, and BHG’s request that the company say publicly it would consider offers was met, if at all, by the strategic review the company announced in March 2024.⁹ Exhibit 1 shows both differences.
Fossil’s results since
Exhibit 2 sets the last quarter Fossil reported before the board seat beside its latest quarter, using the company’s own figures.
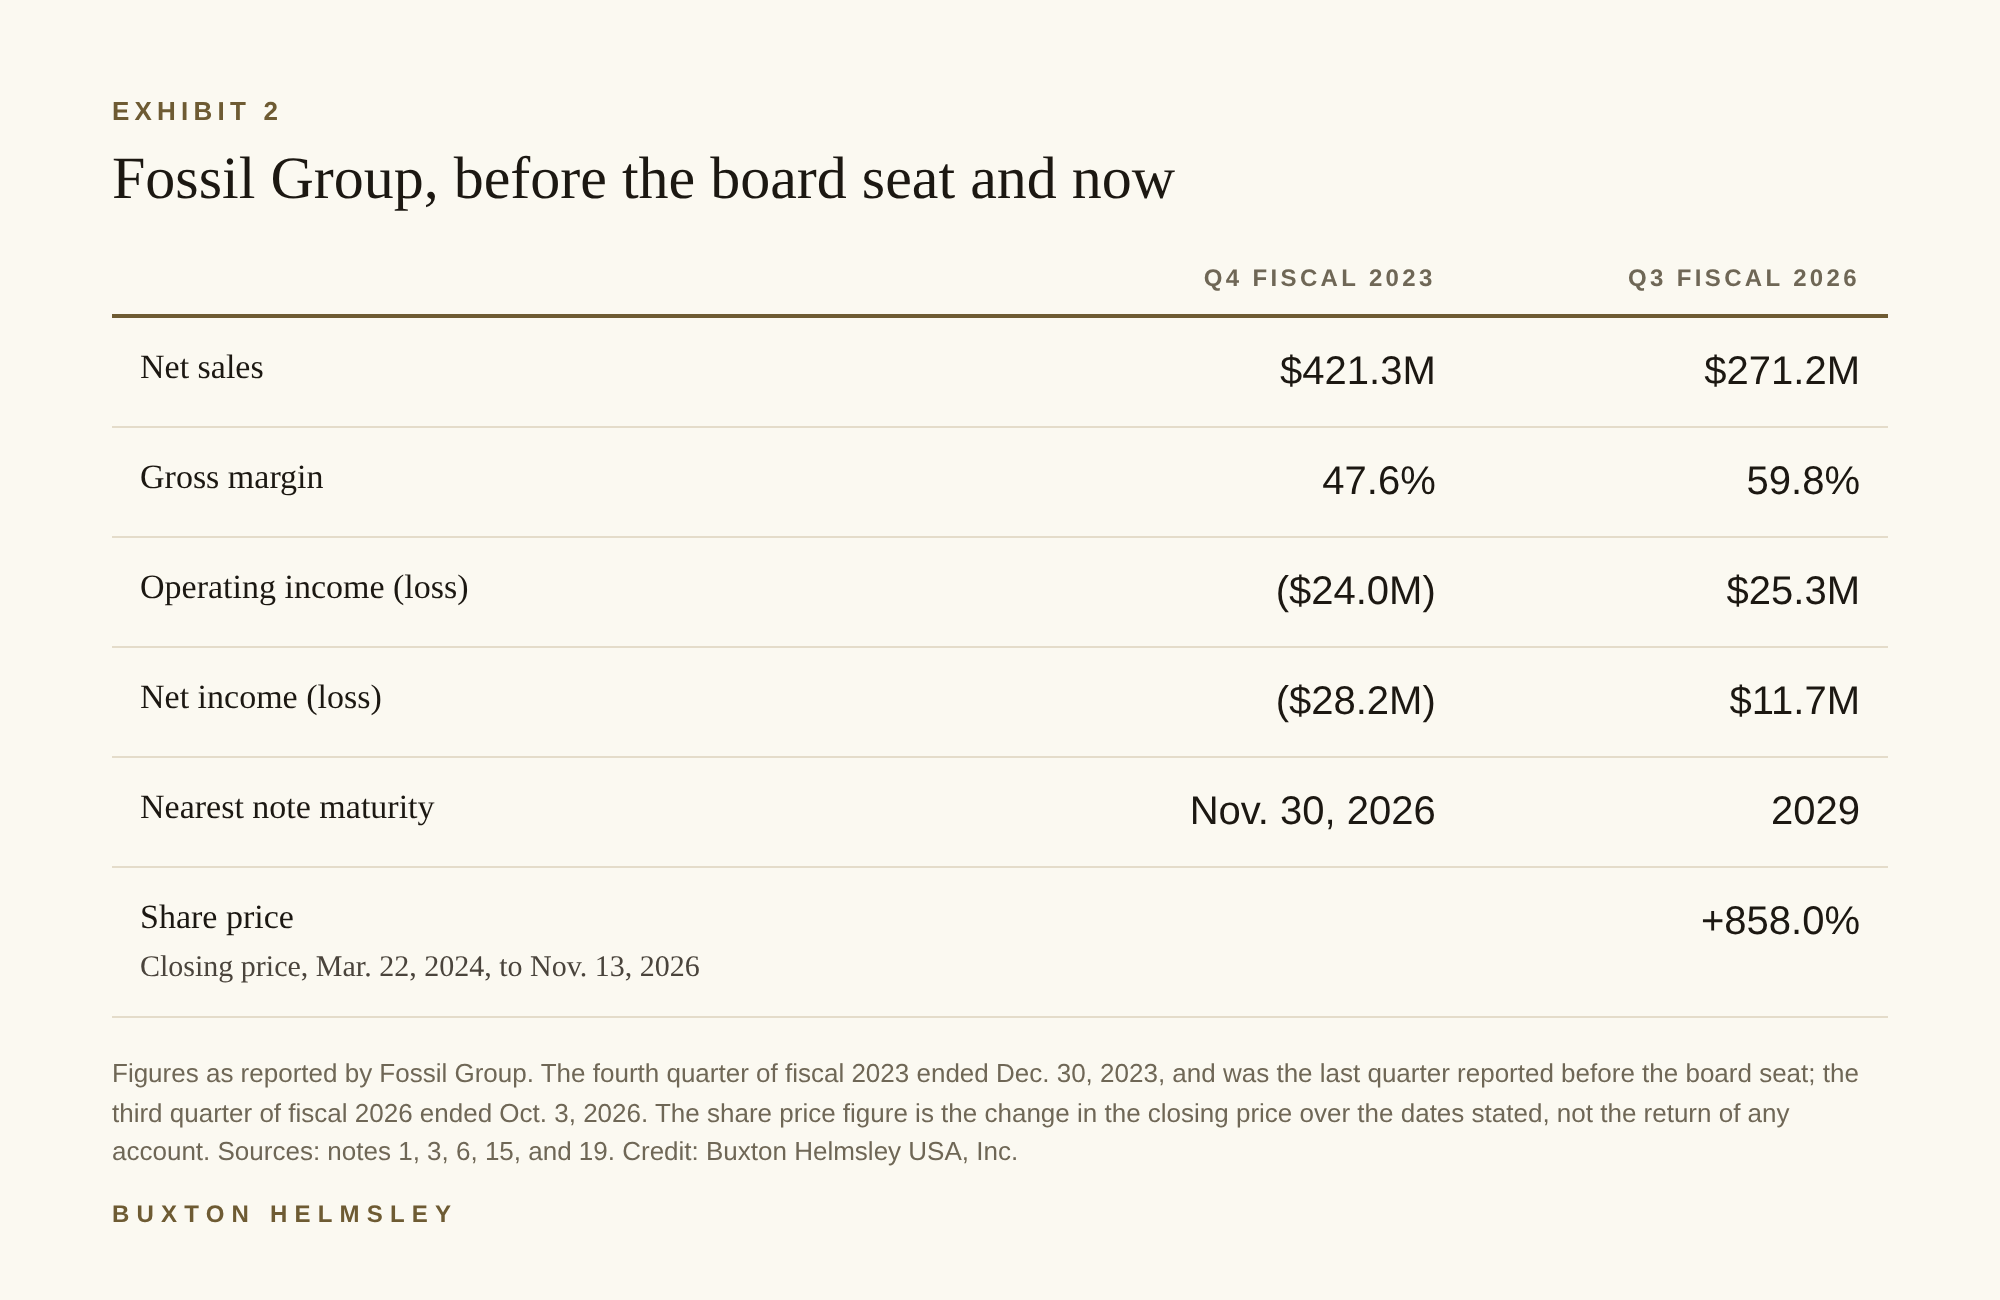
In the fourth quarter of fiscal 2024, the company’s first full quarter under its new Chief Executive Officer, gross margin expanded 630 basis points, to 53.9%, while selling, general, and administrative expense fell 17% and year-end inventory fell 29.4%, to $178.6 million.¹⁵ In the third quarter of fiscal 2026, gross margin reached 59.8%.¹ The company attributed that quarter’s increase partly to lower minimum royalties on licensed brands and the timing of their recognition, and partly to full-price selling, sourcing, and lower tariffs.¹ It also said that about $10 million of wholesale shipments moved from the fourth quarter into the third.²⁰ For that reason, Fossil’s outlook for the full year, an adjusted operating margin of 5.5% to 6.5%, is a better guide to the business than any one quarter.¹
The balance sheet has improved less. At October 3, 2026, Fossil had $77.0 million of cash, $111.7 million of total liquidity, and $208.0 million of debt, and its interest expense in the quarter was more than double the prior year’s, at $8.9 million.¹ The notes that were due in 2026 now fall due in 2029, and they will still have to be repaid or refinanced.
What the record does not prove
The record shows a sequence: a set of measures put to the board in writing, beginning September 15, 2023, and the same measures taken by the company, in substance and largely in that order, between March 2024 and November 2025. It does not show that the engagement caused them, and no one can know what Fossil would have done without it.
The work of the turnaround was done by Fossil’s management and board. Mr. Fogliato and his team wrote the turnaround plan and carried it out, the board approved it, and the noteholders who backed the 2025 restructuring took on risk to make it work. The share price figure above is the change in the closing price of the stock between two dates; it is not the return of any account, and it is measured per share, while the weighted average share count rose about 13% between the third quarters of fiscal 2025 and fiscal 2026.¹ ³
The record does support a narrower claim. In BHG’s assessment in 2023, the binding constraint at Fossil was not the business, whose brands, distribution, and cost base could support a profit, but a board and management that had grown used to a declining position. BHG identified that constraint in writing, proposed specific measures, put forward a turnaround director, and obtained the seat with about 1.4% of the stock and without a contested vote. The constraint was then relieved. A reader can test each of those steps against the letters on the campaign page and the company’s filings, which is why both are cited here.
For boards
Some of this record applies well beyond Fossil.
Most of the fourteen questions asked the company only to confirm its own stated policies or explain its own capital allocation, and a company that answers questions like those in a letter usually hears nothing more about them. When it declines, the refusal tells its board something the filings will not.
Fossil reached an agreement thirty-seven days after the nomination notice. A board that takes a shareholder’s case seriously before a nomination notice arrives can usually settle on better terms, and spend less of its own time doing it.
Fossil did not need a shareholder’s representative on its board. It needed a director who had been through turnarounds before and could help choose a chief executive and a finance chief, approve a cost plan, and deal with noteholders. In a settlement like this one, who takes the seat matters more than how many seats change hands.
The measures here were also specific and dated. A plan that names its targets (a cost figure, a store count, a maturity date) can be checked by anyone, including the board that adopts it.
Related reading
References
[1] Fossil Group, Inc., Exhibit 99.1 to Current Report on Form 8-K, “Fossil Group, Inc. Reports Third Quarter 2026 Financial Results” (November 10, 2026) (primary; supports third-quarter net sales, gross margin and its stated drivers, operating income, net income, liquidity, cash, debt, interest expense, store counts, share counts, the 2026 outlook, and the sale of the European distribution center as a gain on asset divestitures).
[2] Yahoo Finance, Fossil Group, Inc. (FOSL) (secondary; supports the closing price of $9.97 and the change of 26.68% on November 11, 2026).
[3] Closing prices of Fossil Group common stock on the Nasdaq Stock Market on March 22, 2024, and November 13, 2026 (supports the change of 858.0%; the figure is a share price change, not the return of any account).
[4] The Buxton Helmsley Group, Inc., Fossil Group, Inc. campaign page and published correspondence, including BHG’s letters to the board of September 15, September 27, September 29, October 10, and November 28, 2023, and Fossil Group’s letter of October 16, 2023 (primary; supports each quotation and request attributed to the correspondence).
[5] The Buxton Helmsley Group, Inc., press release, “Buxton Helmsley Nominates Four Highly Qualified Directors to Fossil Group Board to Help End Years of Shareholder Suffering” (February 20, 2024) (primary; supports the decline of about 97% since May 2010, the absence of open-market insider purchases in three years, the holding of about 1.4%, and the nominees and their backgrounds).
[6] Fossil Group, Inc., press release, “Fossil Group, Inc. Reports Fourth Quarter and Fiscal Year 2023 Results” (March 13, 2024) (primary, as syndicated; supports fiscal 2023 net sales, operating loss, net loss, fourth-quarter gross margin of 47.6%, and the announcement of a strategic review).
[7] Reuters, “Investor names director candidates at Fossil Group after stock price drop” (February 20, 2024) (secondary; supports the holding of about 1.4% and the four nominees).
[8] The Buxton Helmsley Group, Inc., books-and-records demand under Section 220 of the Delaware General Corporation Law (February 26, 2024) (primary; not publicly available; its withdrawal is confirmed in note 10).
[9] Fossil Group, Inc., press release, “Fossil Group, Inc. Announces Leadership Changes” (March 13, 2024) (primary, as syndicated; supports Mr. Kartsotis stepping down as Chief Executive Officer and as a director, and the strategic review).
[10] Fossil Group, Inc., Current Report on Form 8-K and Cooperation Agreement (March 24, 2024) (primary; supports the agreement, the appointment, the withdrawal of the nomination notice and the books-and-records demand, the standstill and voting provisions, and the expense reimbursement cap).
[11] Fossil Group, Inc., press release, “Fossil Group Announces Appointment of Eugene Davis and Pamela Corrie to Board of Directors” (March 25, 2024) (primary; supports both appointments, effective March 24, 2024, Ms. Corrie’s committee assignment, and the nine nominees for the 2024 annual meeting).
[12] Fossil Group, Inc., Current Report on Form 8-K (filed October 6, 2026) (primary; supports the seven directors elected at the annual meeting of October 2, 2026).
[13] Fossil Group, Inc., Current Report on Form 8-K (filed July 1, 2024) (primary; supports Mr. Doshi’s notice of June 25, 2024, his resignation effective July 19, 2024, and the engagement of Ankura Consulting Group).
[14] Fossil Group, Inc., press release, “Fossil Group, Inc. Appoints Brand Veteran Franco Fogliato as CEO” (September 4, 2024) (primary, as syndicated; supports the appointment effective September 18, 2024).
[15] Fossil Group, Inc., Exhibit 99.1 to Current Report on Form 8-K, “Fossil Group, Inc. Reports Fourth Quarter and Full Year 2024 Results” (March 12, 2025) (primary; supports fourth-quarter gross margin, selling, general, and administrative expense, inventory, the turnaround plan and its targets, and Mr. Greben’s appointment).
[16] Fossil Group, Inc., Exhibit 99.1 to Current Report on Form 8-K, “Fossil Group, Inc. Reports Second Quarter 2025 Financial Results” (August 13, 2025) (primary; supports the gain of about $11 million on the sale of the European warehouse), and The Motley Fool, “Fossil (FOSL) Q2 2025 Earnings Call Transcript” (August 13, 2025) (secondary; supports the sale-leaseback of the German distribution center).
[17] Fossil Group, Inc., Current Report on Form 8-K (filed August 2025), as summarized by TipRanks and Panabee (secondary; supports the transaction support agreement of August 13, 2025, the 59% of noteholders, the $32.5 million of first-out notes due 2029, and the $150 million asset-based facility maturing August 13, 2030).
[18] Harvard Law School Bankruptcy Roundtable, “Distressed Debt Legal Insights: Fossil Group’s UK Restructuring Plan” (March 31, 2026), summarizing Ropes & Gray (secondary; supports the sanction of November 10, 2025, the Chapter 15 recognition two days later, and the description of the transaction as the first known instance).
[19] Weil, Gotshal & Manges LLP, “Weil Acts For Fossil Group As High Court Sanctions Restructuring Plan” (November 19, 2025) (secondary; supports the $150 million of 7.00% senior notes due November 30, 2026, the minimum tender condition of 90%, and the restructuring plan under Part 26A of the Companies Act 2006).
[20] Investing.com, “Earnings call transcript: Fossil beats Q3 2026 estimates and lifts outlook” (November 11, 2026) (secondary; supports the wholesale timing shift of about $10 million from the fourth quarter into the third).
This publication is one of the Insights commentaries of Buxton Helmsley USA, Inc. (“Buxton Helmsley”). It reflects the opinions, analysis, and interpretations of Buxton Helmsley as of the date of publication, and it is based upon information that Buxton Helmsley believes to be accurate and that is derived from public sources or from other sources believed to be reliable. Buxton Helmsley does not represent or warrant that such information is accurate or complete, and it should not be relied upon as such. The views expressed are subject to change at any time, and Buxton Helmsley undertakes no obligation to update this publication or to correct any information contained within it.
Except for statements expressly attributed to an identified source or to a public filing, the statements in this publication constitute the opinions and good-faith analysis of Buxton Helmsley and are not statements of objective fact. Buxton Helmsley’s analysis may rest upon assumptions, estimates, and interpretations that could prove to be incorrect. Any reference to a potential violation, misstatement, impropriety, or deficiency reflects Buxton Helmsley’s analytical conclusions and opinions, and does not represent a finding by any court, regulator, or other authority. Readers should conduct their own investigation and analysis of any company, security, or matter discussed. Any company or person referenced that believes any statement in this publication to be inaccurate is invited to contact Buxton Helmsley at general@buxtonhelmsley.com, and Buxton Helmsley will give good-faith consideration to any correction supported by credible evidence.
This publication is provided for informational purposes only. It does not constitute, and should not be construed as, investment advice, a recommendation, or the provision of any individualized investment advisory service to any person, nor an offer or solicitation to buy, sell, or hold any security. Nothing in this publication takes into account the particular investment objectives, financial situation, or needs of any reader. No reader should construe this publication as creating any advisory, fiduciary, or other relationship between Buxton Helmsley and such reader. Readers should consult their own legal, tax, accounting, and financial advisers before making any investment decision.
As of the date of this publication, Buxton Helmsley, the funds and accounts that it manages or advises, and its principals hold no position in the securities of the companies mentioned in the article. Buxton Helmsley and the foregoing persons may, at any time and without further notice, purchase, sell, cover, or otherwise change any position in any security discussed in this publication, including in a manner inconsistent with the opinions expressed herein, for various reasons, including but not limited to new research discoveries. Buxton Helmsley may realize gains in the event that the price of any security discussed moves in a direction consistent with a position that it holds.
The investor-engagement campaign described in this publication was conducted by The Buxton Helmsley Group, Inc., a company separate from Buxton Helmsley, Inc. and its subsidiaries, and was led by Alexander E. Parker, who is now Chairman and Chief Executive Officer of Buxton Helmsley, Inc. Pamela B. Corrie is a member of Buxton Helmsley’s Expert Advisory Board.
Buxton Helmsley has not received, and will not receive, any compensation from any third party, including any issuer discussed in this publication or any person holding an interest in any such issuer, in connection with the preparation or publication of this commentary, except as expressly disclosed in this publication. Buxton Helmsley was not engaged or compensated by any third party to publish this commentary, except as expressly disclosed in this publication.
This publication is not, and shall not be construed as, an offer to sell or a solicitation of an offer to buy any security or any interest in any fund or other investment vehicle managed or advised by Buxton Helmsley or any of its affiliates, nor is it an advertisement for any such fund, vehicle, or advisory service. Any such offer or solicitation will be made only by means of definitive offering documents, and only to eligible investors, in accordance with applicable law.
This publication is intended only for distribution to, and use by, persons in the United States. It is not directed to, intended for, or to be relied upon by, any person located in any jurisdiction outside the United States, and it does not constitute an offer, solicitation, or provision of any service in any such jurisdiction. Persons who access this publication from outside the United States do so on their own initiative and are responsible for compliance with the laws applicable to them.
This publication may contain forward-looking statements that reflect Buxton Helmsley’s current expectations and that are subject to risks and uncertainties that could cause actual results to differ materially from those expressed. Past performance is not indicative of, and does not guarantee, future results. No representation is made that any investment will achieve, or is likely to achieve, results comparable to those discussed.
To the fullest extent permitted by applicable law, neither Buxton Helmsley nor any of its affiliates, nor their respective principals, members, officers, employees, or agents, shall have any liability to any person for any direct, indirect, incidental, consequential, or other loss or damage arising from any use of, or reliance upon, this publication or any information contained within it.
If any provision of these disclosures is held to be invalid or unenforceable, the remaining provisions shall continue in full force and effect.
© 2026 Buxton Helmsley USA, Inc. All rights reserved. This publication may not be reproduced or redistributed, in whole or in part, without attribution to Buxton Helmsley.